Refinancing Risk 2026: The Sequencing Mistakes That Force a Bad Outcome
A borrower with a facility maturing in eight months starts sounding out lenders in June. A borrower with the same credit profile, the same asset, the same balance sheet, starts in January. Six months apart, nothing else different.
The second borrower runs a competitive process across four lenders and picks the best terms. The first gets one bilateral offer, priced as if the bank is doing them a favour, because by June that is exactly the position they are in.
That gap is refinancing risk in one of its most important and least understood forms. It can arise even where creditworthiness has not materially deteriorated. Credit Market 2026: The Reset covers why lenders are pricing more cautiously across the board this cycle.
This post is about something narrower and more avoidable: the specific points in the calendar where a borrower’s own timing, not the market, closes off options that were available a few months earlier.
The scale of the problem is real. Mortgage Bankers Association data cited by Reed Smith puts $875 billion of US commercial and multifamily mortgage debt maturing in 2026, 17 per cent of the roughly $5 trillion outstanding.
Most of that debt will refinance without drama. The minority that does not tends to share one trait: the borrower treated the maturity date as the start of the conversation rather than the deadline for finishing it.
What Refinancing Risk Actually Means When the Loan Itself Is Fine
Refinancing risk is usually defined as the possibility that a maturing loan cannot be replaced at all. That is the textbook version, and it is rarely what borrowers actually run into.
The more common version is narrower: the loan gets replaced, but on terms materially worse than the borrower’s own credit would otherwise command, because the process that produces competitive terms takes longer than the time left on the clock.
A refinance is not a single event. It is a sequence: internal readiness, lender outreach, indicative terms, credit committee approval, documentation, and close. Each stage has its own lead time, and those lead times do not compress just because a maturity date is approaching.
A borrower who starts the sequence late is not getting a worse version of the same process. They are getting a different, shorter process, with fewer of the steps that produce competitive tension.
The Points Where Optionality Actually Closes
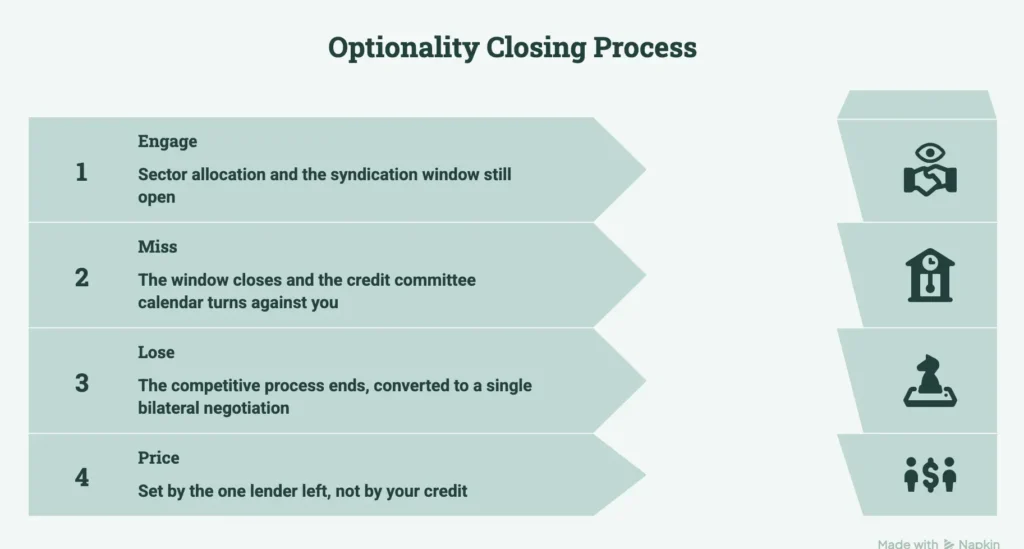
Four specific mechanics determine whether a refinance stays competitive or collapses into a forced bilateral deal, and each closes independently of the borrower’s credit quality.
Sector and portfolio allocation. Banks and institutional lenders manage internal limits on exposure to particular sectors, asset types and risk categories. Those limits are reviewed on cycles that rarely align with an individual borrower’s maturity date.
A lender that would have competed hard for a deal in February can be full on that exposure by September, not because the credit deteriorated but because the allocation did.
The syndication window. Arranging a facility across multiple lenders, rather than accepting whatever a single bank offers, takes lead time to market the deal, collect indications, and build a syndicate.
Left too late, there is no time left to run that process, and the borrower is negotiating with whichever single lender happens to be available, on that lender’s terms.
The credit committee calendar. Approvals move through committees that meet on a schedule, not on demand. Missing a cycle by arriving with an incomplete package does not cost a few days, it costs the interval until the next meeting, and that interval compounds against a maturity date that does not move.
The valuation and documentation runway. A fresh valuation, updated financials and a clean data room all take time to assemble properly.
Produced under maturity pressure, they read as such to a lender’s credit team, and a valuation instructed with weeks rather than months to spare gets less scrutiny from the borrower’s own side before it lands on the lender’s desk.
None of these four points is about whether the lender wants to say yes. They are about whether saying yes is still structurally possible by the time the borrower asks. Special Situations Finance 2026 covers structured capital deployed pre-emptively to preserve exactly this kind of optionality.
What follows here is the mechanical reason that optionality has a shelf life in the first place.
Why Strong Credit Doesn’t Buy Back Time
The instinct, understandably, is that a strong covenant record and a well-performing asset should insulate a borrower from this. They do not, and the reason is structural rather than a comment on the borrower.
A closed sector allocation does not reopen because the applicant has excellent credit. A syndication window that has passed does not extend because the deal would have been easy to place. A missed committee cycle does not get an exception because the borrower’s numbers are strong.
Strong credit changes how attractive a borrower looks once they are in front of a lender with capacity and time to act. It does nothing to create capacity or time that has already been used up elsewhere.
That distinction is what separates refinancing risk as a sequencing problem from refinancing risk as a credit problem, and it is why two borrowers with identical fundamentals can end up in structurally different negotiating positions purely on the basis of when each one started.
What Lenders Actually Watch For
From the lender’s side, the calendar itself is information. A borrower who opens the conversation while there is still enough time to obtain competing indications, complete credit approval and negotiate documentation presents a materially different proposition from one approaching inside ninety days, whatever the underlying numbers say, because a late approach is itself a data point a credit team weighs. It does not automatically signal distress, but it removes the presumption of an orderly process, and pricing follows that presumption as much as it follows the balance sheet.
Lenders also work backward from their own internal deadlines. A committee that needs weeks to approve, a documentation team with its own turnaround, and a syndication desk that needs months to build a book are all fixed constraints from the lender’s side of the table, regardless of how quickly the borrower wants to move once they finally engage.
The Credit Committee Approval Process sets out how that internal mechanism actually works.
Borrowers who understand it plan backward from it. Borrowers who do not find out about it under pressure.
What to Have in Place Before the Clock Starts
Treat the maturity date as the last possible day for close, not the day to start looking. Work backward from it against realistic lender lead times, not the borrower’s own preferred timeline.
Keep a data room and a current valuation refreshable within weeks, not months, so readiness is never the reason a conversation stalls once it starts.
Approach more than one potential lender before committing to a single relationship conversation. A syndication or competitive process only works if there is still time left to run one.
Where the numbers no longer support a straightforward refinance at all, that is a different and more serious problem, covered in Distressed Commercial Real Estate Loans.
Conclusion
Good credit does not eliminate refinancing risk, and good timing does not compensate for fundamentally weak credit. But where the underlying credit remains sound, treating the calendar as a constraint can determine whether the borrower still has competing options when the refinance becomes real.
If you are approaching a facility maturity and want to understand how much runway you genuinely have before your options narrow, we welcome a discreet conversation. Contact us to discuss the position.
For a more structured breakdown of how these strategies are applied in practice, see the Borrower Trust & Due Diligence Playbook.